Mortgage calculator Philippines: your monthly amortization in 30 seconds
A ₱5,000,000 home with 20% down means a ₱4,000,000 loan. Run that through a mortgage calculator for the Philippines at an illustrative 7% over 20 years and the monthly amortization is about ₱31,012, which needs roughly ₱88,606 in gross monthly income to pass a 35% payment-to-income test. Loan, payment and income are the three numbers every lender checks first; this guide shows exactly how they are computed so you can verify any quote.
Quick answer: a ₱5M home, 20% down, 7%, 20 years
- Loan: ₱5,000,000 minus ₱1,000,000 down = ₱4,000,000
- Monthly amortization: about ₱31,012 (total interest about ₱3,442,870)
- Gross monthly income needed at 35%: about ₱88,606
Illustrative, not a quote, as of October 2026. A Philippine "monthly amortization" is the principal-and-interest payment on a housing loan, so a mortgage calculator and an amortization calculator run the same math.
Run your own numbers in the sabahay.ph loan calculator
Skip the arithmetic with our free loan calculator: enter the price, down payment, rate and term, and it returns the monthly payment, total interest and the income you need. Below is the math it runs.
Rates as of October 2026: BSP target rate 5.0% (since 27 August 2026). Pag-IBIG promo 4.5% for loans up to ₱4.9M and 5.75% above that up to ₱10M, fixed for 3 years, for applications filed by 31 December 2026. Published bank rates roughly 7.0% to 8.75% for 1 to 5 year fixed periods (September to October 2026). We use 7% as the illustrative base rate.
This post covers the math. To compare lender tools, see home loan calculators by lender; for the application process, read the complete home loan guide for the Philippines.
The mortgage amortization formula, step by step
Every housing loan calculator in the Philippines uses the standard annuity formula, where M is the monthly payment, P the loan, r the monthly rate (annual rate ÷ 12) and n the number of payments (years × 12):
M = P × r(1 + r)n ÷ ((1 + r)n − 1)
Worked example: ₱4,000,000 at 7% for 20 years
- Loan: ₱5,000,000 − ₱1,000,000 down = P = ₱4,000,000.
- Monthly rate: 7% ÷ 12 = r = 0.0058333.
- Payments: 20 × 12 = n = 240.
- Growth factor: (1.0058333)240 = 4.0387.
- Payment: ₱4,000,000 × 0.0058333 × 4.0387 ÷ (4.0387 − 1) = ₱31,012 a month.
In Excel or Google Sheets it is one cell: =-PMT(0.07/12, 240, 4000000). Banks may round differently or fold insurance into the quote, so expect a small gap.
Proof it works: Pag-IBIG's published examples
Pag-IBIG's 30-year samples (Daily Tribune, June 2026): ₱2.5M at 4.5% = ₱12,667 a month, ₱5M at 5.75% = ₱29,179 and ₱10M at 5.75% = ₱58,357 (versus ₱61,572 at the previous 6.25%). The formula reproduces each to the peso; if two calculators disagree, the inputs differ, not the math.
Mental-math shortcut: payment per ₱1 million borrowed
Multiply your loan in millions by the factor below. A ₱6.4M loan at 7% over 20 years is 6.4 × ₱7,753 = about ₱49,619.
| Rate (illustrative) | 10 years | 15 years | 20 years | 25 years | 30 years |
|---|---|---|---|---|---|
| 6% | ₱11,102 | ₱8,439 | ₱7,164 | ₱6,443 | ₱5,996 |
| 7% | ₱11,611 | ₱8,988 | ₱7,753 | ₱7,068 | ₱6,653 |
| 8% | ₱12,133 | ₱9,557 | ₱8,364 | ₱7,718 | ₱7,338 |
| 9% | ₱12,668 | ₱10,143 | ₱8,997 | ₱8,392 | ₱8,046 |
Monthly principal and interest per ₱1,000,000 borrowed. Illustrative, as of October 2026.
Monthly amortization calculator Philippines: ₱3M, ₱5M, ₱8M and ₱12M homes
Four price points, 20% down and a 7% illustrative rate at 10, 20 and 30 years, plus the gross income a 35% rule requires.
Price-by-term table at 7% with 20% down
| Home price | Loan (80%) | 10 years | 20 years | 30 years | Income needed (20 yr, 35%) |
|---|---|---|---|---|---|
| ₱3,000,000 | ₱2,400,000 | ₱27,866 | ₱18,607 | ₱15,967 | ₱53,163 |
| ₱5,000,000 | ₱4,000,000 | ₱46,443 | ₱31,012 | ₱26,612 | ₱88,606 |
| ₱8,000,000 | ₱6,400,000 | ₱74,309 | ₱49,619 | ₱42,579 | ₱141,769 |
| ₱12,000,000 | ₱9,600,000 | ₱111,464 | ₱74,429 | ₱63,869 | ₱212,653 |
Monthly principal and interest only. Illustrative, not a quote, as of October 2026.
Income you need to qualify (35% rule)
Over 30 years the income bar drops to about ₱45,621, ₱76,035, ₱121,655 and ₱182,483. Two caveats: many banks cap terms at 20 to 25 years (BDO allows 20 for a house and lot, 15 for a condo), though BPI now allows up to 30, and a ₱12M home at 20% down is a ₱9.6M loan, just under Pag-IBIG's new ₱10M ceiling.
What ₱3M to ₱12M buys in Metro Manila
BSP price-index figures cited by Gulf News in August 2026 put a typical Metro Manila condominium at about ₱4.81M and a house at about ₱7.72M, so the ₱5M and ₱8M rows sit mid-market. Supply is also high, with about 80,000 unsold Metro Manila condo units in Q3 2026, down from a record 82,900 in Q2 (Leechiu), and 79,200 at end-2025 by Colliers' count, which gives buyers room to negotiate. Browse homes for sale in the Philippines by price to see what each row buys.
Where your payment goes: interest vs principal
The payment stays the same, but what it buys changes every month: early on, most of it is interest; later, most of it retires the loan. On the ₱4,000,000, 7%, 20-year example, payment number 1 is ₱23,333 interest and only ₱7,679 principal.
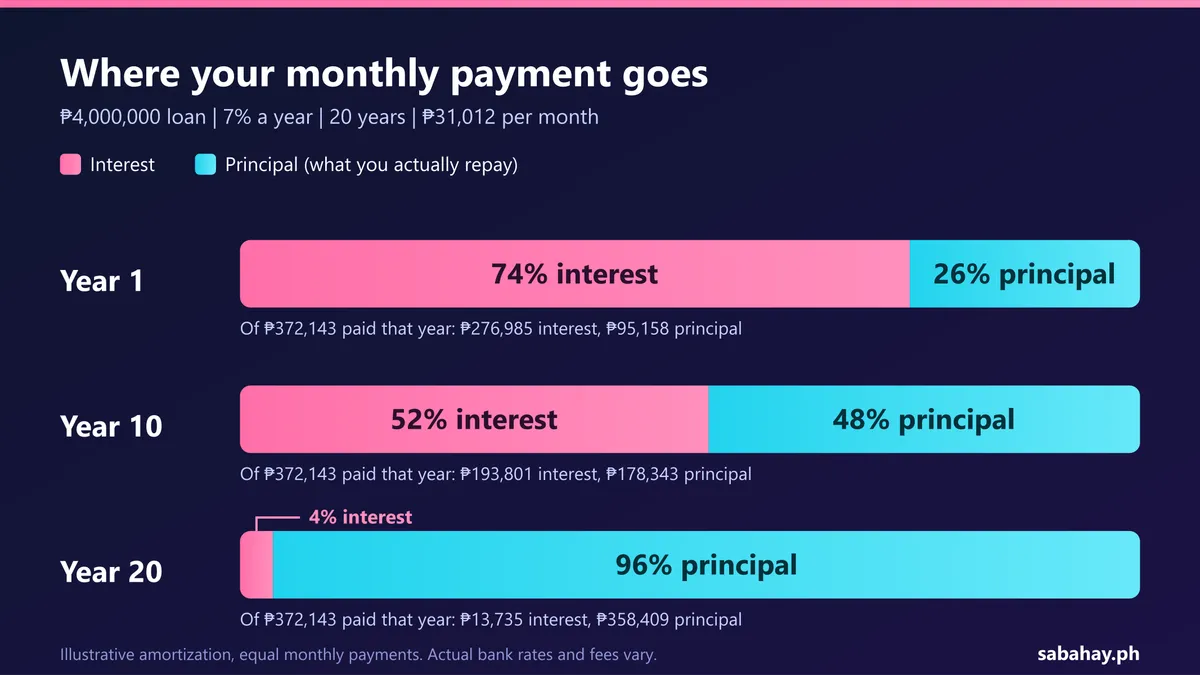
Year 1 vs year 10 vs year 20 on a ₱4M loan
| Loan year | Interest paid | Principal paid | Interest share | Balance at year end |
|---|---|---|---|---|
| Year 1 | ₱276,985 | ₱95,158 | 74% | ₱3,904,842 |
| Year 10 | ₱193,801 | ₱178,343 | 52% | ₱2,670,947 |
| Year 20 | ₱13,735 | ₱358,409 | 4% | ₱0 |
₱4,000,000 at 7% over 20 years, ₱31,012 a month. Illustrative, as of October 2026.
Principal first exceeds interest at payment number 122, just past the ten-year mark. After five years and about ₱1.86M in payments, the balance is still ₱3,450,265, which is why early extra payments matter so much.
Why extra payments in the early years save the most
- Add ₱5,000 a month: the loan ends in 180 months (15 years) and total interest falls by about ₱979,000.
- Add one full payment a year (from your 13th-month pay, say): the loan is paid off in 205 months, saving about ₱561,000.
Check your prepayment terms first; some lenders charge a penalty for paying ahead during a fixed-rate period.
How down payment, term and interest rate change your payment
Three levers move any mortgage calculator result.
Down payment: 5%, 10%, 20% or 30%
On a ₱5,000,000 home at 7% over 20 years:
- 5% down (loan ₱4.75M): ₱36,827 a month
- 10% down (loan ₱4.5M): ₱34,888
- 20% down (loan ₱4.0M): ₱31,012
- 30% down (loan ₱3.5M): ₱27,135
Banks typically lend up to 80% of appraised value, so 20% down is the standard planning assumption; Pag-IBIG's Expanded 4PH program can finance up to 100% of appraised value for qualified borrowers.
Loan term: 10 to 30 years
| Term | Monthly payment | Total interest |
|---|---|---|
| 10 years | ₱46,443 | ₱1,573,207 |
| 15 years | ₱35,953 | ₱2,471,564 |
| 20 years | ₱31,012 | ₱3,442,870 |
| 25 years | ₱28,271 | ₱4,481,350 |
| 30 years | ₱26,612 | ₱5,580,356 |
₱4,000,000 loan at 7%. Illustrative, as of October 2026.
Going from 20 to 30 years cuts the payment by about ₱4,400 a month but adds about ₱2.14M of interest. If you need the longer term, pair it with the extra-payment habit above.
Interest-rate sensitivity: 6%, 7%, 8% and 9%
| Rate | 20-yr payment | 20-yr total interest | 30-yr payment | Income needed (20 yr, 35%) |
|---|---|---|---|---|
| 6% | ₱28,657 | ₱2,877,738 | ₱23,982 | ₱81,878 |
| 7% | ₱31,012 | ₱3,442,870 | ₱26,612 | ₱88,606 |
| 8% | ₱33,458 | ₱4,029,825 | ₱29,351 | ₱95,593 |
| 9% | ₱35,989 | ₱4,637,369 | ₱32,185 | ₱102,826 |
₱4,000,000 loan. Scenario rates, not quotes, as of October 2026.
On a ₱4M, 20-year loan, each extra percentage point adds roughly ₱2,350 to ₱2,530 a month: about ₱28,000 to ₱30,000 a year, or ₱565,000 to ₱608,000 more interest over the life of the loan.
The rate in your calculator is not the rate for 20 years
Philippine housing loans are rarely fixed for the full term. Bank loans are usually fixed for 1 to 5 years and then repriced at the bank's prevailing rate, some of them annually after that; Pag-IBIG's promo rates are fixed for 3 years. A low introductory "honeymoon" rate flatters the calculator, so always run a second scenario at a higher rate.
What the BSP's 2026 hikes mean for borrowers
The Bangko Sentral cut its target rate to 4.25% on 19 February 2026, then raised it at its April and June meetings and again on 27 August, to 5.0%. Headline inflation hit 7.2% in September 2026, up from 6.1% in August, and the BSP's central forecasts put average inflation at 6.1% for 2026 and 5.4% for 2027 (BSP Monetary Policy Report, August 2026). The remaining Monetary Board meetings this year are scheduled for 22 October and 17 December, so rate risk is live.
The BSP's Q1 2026 property price report also noted tighter bank credit standards for housing loans (BSP Residential Property Price Index, Q1 2026), so compare the fixing period as carefully as the headline rate.
Repricing example: what happens after year 3
| Scenario (math, not a forecast) | Balance at repricing | New rate | New payment | Change |
|---|---|---|---|---|
| Bank, ₱4M at 7%, 20 yr, fixed 3 yr | ₱3,693,392 | 6% for 17 yr | ₱28,923 | −₱2,089 |
| Same loan | ₱3,693,392 | 8.5% for 17 yr | ₱34,285 | +₱3,273 |
| Same loan | ₱3,693,392 | 9% for 17 yr | ₱35,412 | +₱4,400 |
| Pag-IBIG, ₱5M at 5.75%, 30 yr, fixed 3 yr | ₱4,795,419 | 7% for 27 yr | ₱32,984 | +₱3,805 |
| Same loan | ₱4,795,419 | 8% for 27 yr | ₱36,171 | +₱6,992 |
Original payments ₱31,012 (bank) and ₱29,179 (Pag-IBIG). Illustrative, as of October 2026.
Budget for the 9% row (base rate plus 2 points), not the base row. If your income only clears the 35% test at ₱31,012, you are betting that rates will not move.
Pag-IBIG promo vs a bank loan: same formula, different inputs
The formula does not care who lends; the rate, term and loan ceiling do.
Pag-IBIG's current rates and ₱10M ceiling
- Promo rates (Circular 494): 4.5% for loans up to ₱4.9M and 5.75% above ₱4.9M up to ₱10M, fixed for 3 years and then repriced, for new applications filed by 31 December 2026. (The first reports cited ₱2.5M; later ones use ₱4.9M.)
- Maximum loan: ₱10,000,000, raised from ₱6,000,000 in May 2026, subject to credit evaluation and appraisal.
- Term: up to 30 years, provided you are no older than 65 at application and no older than 70 at loan maturity.
- Capacity to pay: amortization capped at 35% of gross monthly income; up to two other Pag-IBIG members can combine incomes in a tacked loan.
Side-by-side on the same ₱4M loan
| Lender (illustrative) | Rate | Term | Monthly payment | Income needed (35%) | Total interest* |
|---|---|---|---|---|---|
| Pag-IBIG promo | 4.5% (fixed 3 yr, then repriced) | 30 years | ₱20,267 | ₱57,907 | ₱3,296,268 |
| Bank | 7% (fixed 1 to 5 yr, then repriced) | 20 years | ₱31,012 | ₱88,606 | ₱3,442,870 |
₱4,000,000 loan. *Total interest assumes the starting rate never changes, which neither loan guarantees. Pag-IBIG promo rate for applications through 31 December 2026; bank rate illustrative, as of October 2026.
The ₱10,745 monthly gap comes from the lower rate and the longer term in roughly equal parts: at 4.5% over 20 years the payment would be about ₱25,306. Because the promo reprices after year 3, run the repricing table before you commit. Under Expanded 4PH, a ₱950,000 socialized-housing loan at the subsidized 3% over 30 years is about ₱4,005 a month, versus ₱5,849 at the regular 6.25%. See our Pag-IBIG housing loan requirements and steps and the housing loan guide for OFWs, and confirm current terms on the official Pag-IBIG housing loan page.
Will the lender approve your payment? The 35% rule and your income
Pag-IBIG's guidelines are explicit: the monthly amortization must not exceed 35% of gross monthly income (Circular 402 of 2018, repeated in its July 2026 Expanded 4PH presentation). Banks set their own ceilings, commonly cited at 30% to 40%, and will look at your other loan payments too. Required gross income = monthly amortization ÷ 0.35, so ₱31,012 ÷ 0.35 = ₱88,606.
How to get under the line
- Raise the down payment before raising your budget: 30% instead of 20% on the ₱5M home trims about ₱3,900 a month.
- Lengthen the term, then prepay voluntarily when cash flow allows.
- Pay down revolving debt before applying, or add a co-borrower where the lender allows it.
What a mortgage calculator leaves out
A calculator shows principal and interest only; your real monthly and upfront costs are higher.
Insurance, fees and closing costs
- Mortgage redemption and fire insurance: required on bank-financed homes; premiums depend on the loan amount and, for the life cover, your age.
- Processing and appraisal fees: one major bank's published schedule lists ₱10,000 for processing plus ₱5,000 for appraisal (as of October 2026).
- Documentary stamp tax on the loan: ₱1.50 per ₱200 borrowed, or 0.75% of the loan (₱30,000 on ₱4M).
- Transfer and registration costs, notarial fees and association dues.
A rule of thumb from REN.ph is to budget about 3% to 5% of the price for closing costs plus 1% to 2% of the loan for lender fees. On a ₱5M home with a ₱4M loan, that is roughly ₱150,000 to ₱250,000 in closing costs and ₱40,000 to ₱80,000 in fees.
Your right to a written breakdown
Under the Truth in Lending Act (Republic Act 3765), the lender must give you a written statement before the loan is consummated, showing the amount financed, itemized charges and the finance charge in pesos and as a simple annual rate. Ask for it, along with the full amortization schedule.
Mortgage calculator checklist before you apply
Five numbers to confirm with your lender
- Loan amount and loan-to-value: what share of the appraised value they will finance.
- Interest rate and fixing period: fixed for how long, and how repricing works after that.
- Total term: and any age limit at maturity.
- Monthly amortization including insurance: the all-in figure.
- Upfront fees: processing, appraisal, DST and transfer costs, in writing.
Then run three scenarios in the sabahay.ph loan calculator: the base case, the base rate plus 2 points, and a shorter term. If all three fit your budget, browse homes for sale by price band and match listings to the price table above.
Disclaimer: all figures are illustrative estimates as of October 2026, not financial advice or a loan offer; your lender's figures will differ.
Frequently Asked Questions
How do I compute my monthly mortgage amortization in the Philippines?
Use M = P × r(1 + r)^n ÷ ((1 + r)^n − 1), where P is the loan, r the annual rate ÷ 12 and n the number of months. For ₱4,000,000 at 7% over 20 years: r = 0.0058333, n = 240 and (1 + r)^240 = 4.0387, so M is about ₱31,012. In Excel or Google Sheets: =-PMT(0.07/12,240,4000000).
How much is the monthly amortization for a ₱3 million house or condo?
With 20% down the loan is ₱2.4M. At an illustrative 7% (October 2026) that is ₱27,866 a month over 10 years, ₱18,607 over 20 or ₱15,967 over 30, principal and interest only. At Pag-IBIG's 4.5% promo over 30 years it is about ₱12,160 (fixed for 3 years; apply by 31 December 2026). Income needed at 35% for the 20-year bank case is about ₱53,163.
What salary do I need for a ₱5 million home loan?
A ₱5M home with 20% down is a ₱4.0M loan. At 7% over 20 years the payment is ₱31,012, so at a 35% ratio you need about ₱88,606 in gross monthly income (₱95,593 at 8%). Pag-IBIG caps amortization at 35% of gross income; banks commonly use 30% to 40%. Under the Pag-IBIG 4.5% promo over 30 years the payment is ₱20,267, needing about ₱57,907.
What are home loan interest rates in the Philippines right now (October 2026)?
Pag-IBIG's promo for new applications filed by 31 December 2026 is 4.5% for loans up to ₱4.9M and 5.75% above ₱4.9M up to ₱10M, fixed for 3 years and then repriced, plus a subsidized 3% under Expanded 4PH for socialized housing. Published bank rates were roughly 7.0% to 8.75% for 1 to 5 year fixed periods as of 1 September 2026, and the BSP target rate has been 5.0% since 27 August 2026. Confirm current quotes with your lender.
How much down payment do I need for a home loan in the Philippines?
Banks typically lend up to 80% of appraised value, so plan on about 20% down; Pag-IBIG's Expanded 4PH can finance up to 100% for qualified borrowers. On a ₱5M home at 7% over 20 years the payment is ₱36,827 with 5% down, ₱34,888 with 10%, ₱31,012 with 20% and ₱27,135 with 30%. Closing costs are separate; a common rule of thumb is 3% to 5% of the price.
Is a 20-year or 30-year mortgage better?
On a ₱4.0M loan at 7%, 20 years costs ₱31,012 a month with ₱3.44M total interest, while 30 years costs ₱26,612 with ₱5.58M. That saves about ₱4,400 a month but adds about ₱2.14M of interest. Many banks cap terms at 20 to 25 years (BPI allows 30); Pag-IBIG allows up to 30 if you are no older than 70 at loan maturity. A middle path is a longer term plus voluntary prepayments.
Does the mortgage calculator include insurance and fees?
No. A calculator shows principal and interest only. Bank-financed homes also require mortgage redemption and fire insurance, plus processing and appraisal fees, documentary stamp tax on the loan (0.75%) and transfer and registration costs. Under the Truth in Lending Act (RA 3765), the lender must state the finance charge in writing, in pesos and as a simple annual rate, before the loan is consummated.