The best places to invest in real estate in the Philippines in 2027 depend on what you need the property to do. For prime value and resale liquidity: Taguig (BGC) and the Makati CBD. For higher gross rental yield, with oversupply risk: the Pasig–Ortigas–Mandaluyong belt and Manila City. For growth corridors: Cavite, Batangas and Pampanga–Clark. Among regional cities: Cebu for rentals and Davao for land. For retirement: Dumaguete and the Batangas lake towns.
The market is moving at three speeds, so every figure here is dated and sourced (as of October 12, 2026). The Bangko Sentral ng Pilipinas (BSP) Residential Property Price Index (RPPI) for Q2 2026 shows nationwide prices up just 0.4% year on year, the slowest since the series began in 2019: Metro Manila condos rose 7.4% while provincial house prices fell.
Educational content, not financial advice. Run your own numbers and consult a licensed professional before you buy.
What changed for property investors going into 2027
Rates, inflation and the peso
The BSP raised its policy rate to 5.0% on August 27, 2026, its third straight hike, and Nomura expects another 25 basis points at the October 22 meeting. Inflation hit 7.2% in September, and the BSP's August 2026 Monetary Policy Report projected averages of 6.1% for 2026 and 5.4% for 2027. GDP grew only 2.3% in Q2 2026. The peso closed at a record low of ₱62.90 per US dollar on October 8, 2026, a lift for OFW and dollar budgets. More in our 2027 Philippine real estate market outlook.
Prices: Metro Manila condos up, provincial houses down
The BSP RPPI for Q2 2026, year on year:
- Nationwide +0.4%: NCR +5.2%, areas outside NCR −2.7%.
- Condominiums +6.0% (NCR +7.4%, outside NCR +3.4%); houses −4.1%.
- By area: Balance Greater Manila Area (Batangas, Bulacan, Cavite, Laguna, Pampanga, Rizal) −3.0%; Metro Cebu −0.2% (condos +6.4%, houses −6.7%); Metro Mindanao +2.1% (condos −1.7%, houses +4.6%).
Real estate investment in the Philippines in 2027 rewards picking the right segment in the right city, not a bet on the whole country.
Supply: the Metro Manila condo overhang
Colliers Philippines put Metro Manila condo vacancy at 24.9% in Q2 2026 (24.7% at end-2025), heading for a record 25.6% by end-2026 before easing from 2027 as completions slow (its earlier forecast put 2027 at about 23.9%). Colliers counted 79,200 unsold units at end-2025, and its unsold ready-for-occupancy (RFO) count rose to 32,600 in Q2 2026; Leechiu counted a record 82,900 unsold condos in Q2, easing to about 80,000 in Q3. Unsold stock is concentrated in Cubao–New Manila, Manila, the Bay Area, Pasig and Alabang–Las Piñas.
Financing: the ₱10M Pag-IBIG ceiling
Pag-IBIG's housing loan ceiling is now ₱10 million, up from ₱6 million. Promo rates of 4.5% (loans up to ₱4.9M) and 5.75% (above ₱4.9M to ₱10M), fixed for three years, apply to applications filed by December 31, 2026. BPI's indicative bank rates run from 7.00% (one-year fixing) to 8.00% (five-year). Developers defend headline prices with no-spot-down-payment deals and five- to 10-year equity terms (Cushman & Wakefield).
Best places to invest in real estate in the Philippines in 2027: the scorecard
We rate the best cities to invest in real estate in the Philippines on yield, price momentum, supply and catalysts, plus a data grade: A where the BSP, Global Property Guide (GPG) and a consultancy all publish figures, C where evidence is thin. GPG yields compare asking rents with list prices; net runs 1.5 to 2 points lower. Leechiu Property Consultants' (LPC) institutional yields are lower still: 3.8% on primary and 4.6% on secondary units (Q1 2026). We never average sources, and "n/a" means no reliable figure exists.
| Location | Gross yield (GPG) | Momentum and supply | Demand signal or catalyst | Best for | Data |
|---|---|---|---|---|---|
| Taguig–BGC | 4.70–4.80% | Prime prices +19.9% (Knight Frank) | Rents above pre-pandemic (LPC) | Capital preservation | A |
| Makati CBD | n/a | Vacancy 13.2% vs 23.9% Metro Manila (end-2024) | Prime launches 92–100% sold | Scarcity, appreciation | B |
| Pasig, Mandaluyong, San Juan | Pasig 4.00–6.19%; Mandaluyong up to 8.70%; San Juan 7.21–7.70% | Pasig high inventory | Ortigas office vacancy to single digits (CBRE) | Rental yield | A |
| Quezon City | 4.35–5.05% | Cubao–New Manila high inventory | MRT-7; Subway demo run (2028) | Student, mid-ticket rentals | A |
| Manila City | 6.18% average | High inventory | n/a | Yield (slow resale) | B |
| Cavite | n/a | House-and-lot 95% sold; Balance GMA −3.0% (BSP) | LRT-1 Cavite Extension, CALAX | First-time, OFW buyers | B |
| Laguna | n/a | House-and-lot 92% sold | NSCR, Calamba terminus | House-and-lot, lots | C |
| Batangas | n/a | House-and-lot 89% sold | Lipa diversion road; San Benito estate | Leisure, retirement | B |
| Pampanga–Clark | n/a | Clark office vacancy 22.5% (Savills) | Manila–Clark Railway (2028) | Long-horizon land | C |
| Rizal–Antipolo | n/a | Fastest population growth in Luzon, 2020–2024 (PRIME) | MRT-4 financing only in 2030 | Retirement | C |
| Cebu | 5.08% (Cebu City) | Condos +6.4%, houses −6.7% (BSP) | BRT partial operations since March 2026 | Short-term rental | A |
| Davao | n/a | Condos −1.7% (BSP); lots +13–15% a year | Bypass road, Samal bridge (2028) | Land | B |
| Iloilo, Bacolod, Dumaguete | n/a | Office demand mixed (Savills) | Dumaguete ecozone proposed | Patient capital | C |
Metro Manila: where condos still make sense in 2027
Taguig and BGC
Metro Manila ranked 2nd in Knight Frank's Prime Global Cities Index for Q1 2026, with prime prices up 19.9% year on year. Taguig posts the highest luxury resale asking price at ₱864,000 per sqm, but typical BGC units cost far less: Lamudi lists a 35 sqm studio at ₱10M to ₱11.6M, roughly ₱286,000 to ₱331,000 per sqm. With gross yields of 4.70% to 4.80%, dues of ₱90 to ₱160 per sqm a month and most tickets above the Pag-IBIG cap, BGC is a capital-preservation play, not an income play. Compare towers among Taguig and BGC properties for sale.
Makati CBD
Makati's case is scarcity. Colliers reported CBD residential vacancy of 13.2% against 23.9% for Metro Manila at end-2024 (older data). Prime launches Balmori Suites (₱690,000 per sqm) and Edades West (₱554,000 per sqm) are 92% to 100% sold, and Makati still commands Metro Manila's highest office rents (CBRE). No Makati-specific yield is published.
Pasig, Ortigas, Mandaluyong and San Juan
This belt posts the highest asking-price yields: Pasig two-bedrooms at 6.19%, Mandaluyong studios and one-bedrooms at 8.70%, and San Juan small units at 7.21% to 7.70%. CBRE expects Ortigas office vacancy to reach single digits by end-2026 as cost-conscious tenants leave Makati and BGC. But Pasig is on Colliers' high-inventory list, and MRT-4 financing approval is not scheduled until 2030. Check two-bedroom prices among Pasig condos for sale first.
Quezon City
Yields of 4.35% to 5.05% sit mid-pack. Katipunan student condos priced ₱2M to ₱11M were nearly 60% sold at Q4 2025 (Colliers), and transit upside comes from MRT-7 (2027 target) and the Metro Manila Subway, about 60% complete in July 2026 with a demonstration run targeted for 2028. Cubao–New Manila, though, carries heavy unsold stock.
Manila City
Manila City has the highest GPG average yield in our set at 6.18%, at a crowdsourced centre price of about ₱275,500 per sqm (Numbeo, small sample). It is also one of Colliers' high-inventory areas: the rent may be good, but the exit may be slow.
Luzon growth corridors: Cavite, Laguna, Batangas and Pampanga
Calabarzon is where families and OFW households buy. Colliers reports end-2025 house-and-lot take-up of 95% in Cavite, 92% in Laguna and 89% in Batangas, and the Cavite–Laguna–Batangas share of residential loans reached 30% in 2024 while NCR's fell to 29% from 48% in 2019 (BusinessWorld, June 2026). But take-up is not appreciation. Balance Greater Manila Area prices fell 3.0% in Q2 2026, and Colliers' average house-and-lot price rose only from ₱3M in 2016 to ₱3.5M in 2025, about 1.7% a year, while lot-only projects gained 5% to 13% a year. Land has the stronger record.
Cavite
Cavite's population grew 1.51% a year from 2020 to 2024, second only to Rizal in Luzon (PRIME Philippines), helped by the LRT-1 Cavite Extension and CALAX. Price in the entry-level supply wave: Megawide, backed by a ₱10B Pag-IBIG investment, is building 7,143 socialized units in Dasmariñas due within two years, with amortization from ₱2,500 a month.
Laguna
Laguna's long-range catalyst is the North–South Commuter Railway, which ends in Calamba. The line targets partial operations by December 2027 and full operations by Q3 2033 (secondary sources), with no confirmed opening order. Lacking yield or price data, Laguna is a grade-C pick.
Batangas
Lipa's population grew more than 70% in two decades, the Lipa City–Mataas na Kahoy Diversion Road opened in 2026, and Megaworld is building the 25-hectare, ₱12B San Benito wellness estate. With Taal Lake nearby, Batangas is Luzon's retirement and second-home pick.
Pampanga and Clark
Central Luzon's economy grew 6.5% in 2024, and Colliers cites the Manila–Clark Railway (2028) and the New Manila International Airport in Bulacan (beyond 2028) as catalysts. Clark office vacancy was still 22.5% after net demand shrank in late 2025 (Savills), and no reliable residential yield exists. For provincial lots, check the title and agrarian-reform restrictions before reserving.
Regional cities: Cebu, Davao, Iloilo, Bacolod and Dumaguete
Cebu
Cebu City averages 5.08% gross (GPG), at a crowdsourced centre price of about ₱183,000 per sqm (Numbeo). The BSP shows a split market: Metro Cebu condos +6.4%, houses −6.7%. With more than 92,300 condo units, the largest cluster outside the capital, condo buyers can negotiate while house-and-lot sellers hold firm (Lamudi, citing Colliers).
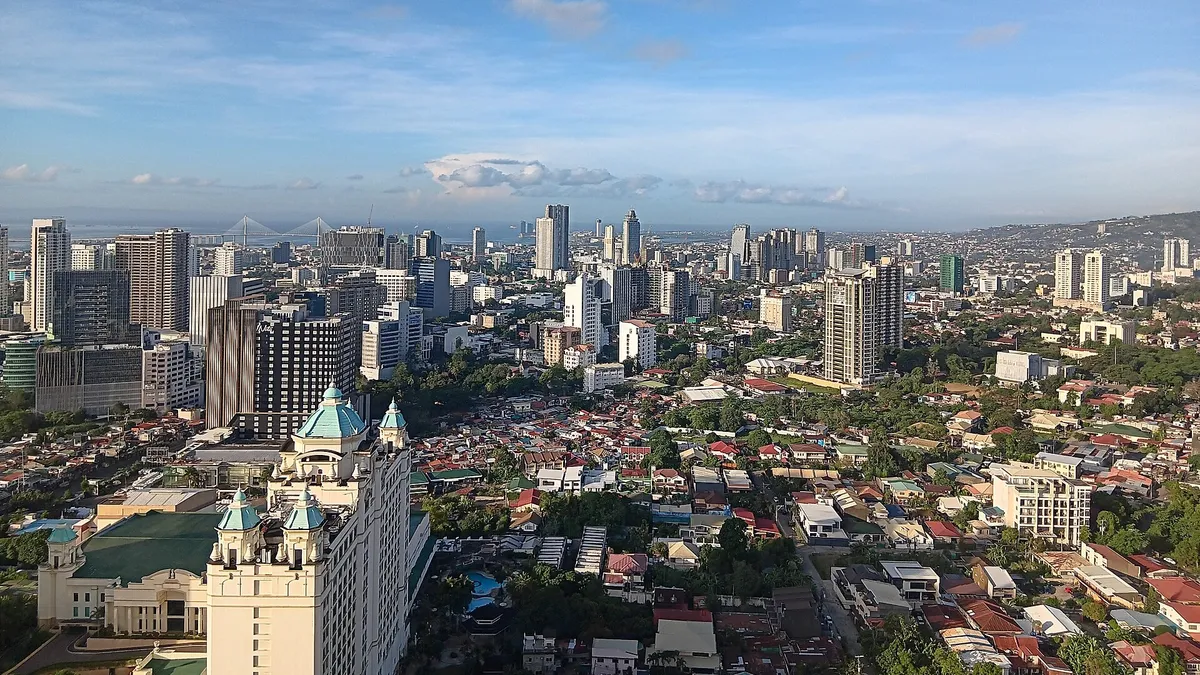
The Cebu BRT began partial operations in March 2026. The risk is office demand, which drives BPO renters: CBRE says it fell 68.2% in H1 2026, with vacancy at 13.9% in June heading to 18% to 22% by year-end. Tourism (5.1 million visitors in 2024) supports Mactan short-term rentals. See our Cebu City area guide for neighborhoods.
Davao
Colliers reports Davao condo take-up of 87% at end-2025, house-and-lot take-up of 96% in Davao del Sur, and lot prices in Davao and Northern Mindanao up 13% to 15% a year from 2016 to 2025. The Davao City Bypass Road and Davao–Samal Bridge are targeted for 2028. The cautions: Metro Mindanao condo prices fell 1.7% (BSP), condo stock rises from 27,760 to 41,870 units by end-2029, and no reliable rental yield exists, so the case is land.
Iloilo, Bacolod and Dumaguete
Savills says Iloilo was the only regional hub to add office space in 2025 (24,000 sqm) and kept positive net take-up, while Bacolod's was negative. Alveo is launching its first village in Talisay, Negros Occidental, and Dumaguete has a proposed economic zone and a university base. None has verified yield or price data.
Where to invest in real estate in the Philippines by goal
- Rental yield: two-bedrooms in Pasig and Mandaluyong (6.19% to 7.28% gross) and Manila City (6.18%), before costs and with oversupply risk.
- Appreciation: prime Taguig and Makati condos; for land, lot-only projects in Calabarzon, Central Luzon and Davao, up 5% to 15% a year in 2016–2025 (Colliers).
- Retirement: Dumaguete, Lipa and Taal Lake, or Antipolo, where LRT-2 reaches Masinag.
- Short-term rental: Mactan and Cebu City; check condo-corporation and LGU rules on short stays first.
- First-time buyers: Cavite and Batangas house-and-lot within the Pag-IBIG ceiling, or RFO condos in Cebu, Quezon City and Pasig, where unsold stock gives you room to negotiate.
- OFWs: Calabarzon and Central Luzon house-and-lot financed through Pag-IBIG. The weak peso helps, but inspect before you pay; see our guide to buying property from abroad.
Risks and costs every investor should price in
The biggest 2027 risk is negative carry. As a simplified illustration, not a sourced fact: a ₱5,000,000 condo at 4.7% gross earns about ₱235,000 a year, or roughly ₱135,000 to ₱160,000 after the 1.5- to 2-point cost haircut. Interest alone on a ₱4,000,000 loan is about ₱320,000 a year at BPI's indicative 8.00% five-year rate, and about ₱180,000 even at Pag-IBIG's 4.5% promo. Leveraged rental buyers lose money unless prices rise or rates fall.
- Closing costs: Documentary Stamp Tax 1.5%, transfer tax up to 0.75% in Metro Manila (up to 0.50% in provinces), registration about 0.25% to 0.50%, and 12% VAT on developer sales above ₱3.6M; the seller normally pays the 6% capital gains tax. Budget roughly 3% to 5% above the price for taxes, registration and fees, and more if the 12% VAT applies.
- Holding costs: condo dues, real property tax plus the 1% Special Education Fund levy, and the RPVARA reform (RA 12001), which caps the first-year increase under a new schedule of market values at 6%. House Bill 10808, pending as of September 28, 2026, would suspend parts of it for two years.
- Flood exposure: check hazard maps and homeowners' association records for lowland sites.
- Foreign buyers: under the Condominium Act (RA 4726), foreigners cannot own land, and condo projects must stay within a foreign-ownership limit applied as 40%; RA 12252 (2025) allows investor land leases of up to 99 years. See our foreigner property buying guide.
- Due diligence: verify the DHSUD License to Sell for pre-selling and the title chain for resales. Foreclosed homes are a separate route that bank lending barely touches (0.4% of bank housing loans in Q2 2026, per the BSP); browse the Pag-IBIG foreclosed properties database.
2027 watchlist: dates that can move prices
- October 22 and December 17, 2026: BSP Monetary Board meetings; a fourth straight hike is possible.
- December 31, 2026: deadline for Pag-IBIG's promo rates, unless extended.
- 2027: MRT-7 target, NSCR partial operations by December, and Colliers' forecast of vacancy easing from a record 25.6% end-2026 peak.
- 2028: Subway demonstration run, Manila–Clark Railway, Davao bypass and Samal bridge targets.
Rail dates slip, so underwrite on today's access, then test the carry in our loan calculator at bank and Pag-IBIG rates.
Frequently Asked Questions
What is the best place to invest in real estate in the Philippines in 2027?
It depends on your goal. Taguig–BGC and Makati CBD lead for prime value and resale liquidity. Pasig two-bedrooms (6.19%) and Manila City (6.18%) top Global Property Guide's gross yields, with oversupply risk. Cavite, Laguna and Batangas suit growth buyers, with 89% to 95% house-and-lot take-up (Colliers, end-2025). Cebu suits rentals, Davao land. Not financial advice.
Which Philippine city has the highest rental yield?
On Global Property Guide asking-price data, Mandaluyong leads at 8.70% for studios and one-bedrooms, followed by San Juan (7.21% to 7.70%), Pasig two-bedrooms (6.19%) and Manila City (6.18%). The Metro Manila average is 5.46%. These are gross; net runs 1.5 to 2 points lower, and Leechiu's institutional yields were 3.8% to 4.6% in Q1 2026.
Is it a good time to buy property in the Philippines in 2027?
Signals are mixed. The BSP policy rate is 5.0%, inflation hit 7.2% in September 2026, and bank fixed rates of 7.00% to 8.00% exceed most gross yields, so leveraged rental buyers face negative carry. But 32,600 unsold RFO condos (Colliers, Q2 2026) give buyers bargaining power, and Pag-IBIG's promo rates of 4.5% and 5.75% run until December 31, 2026.
Is Metro Manila oversupplied with condos?
In several sub-markets, yes. Colliers puts vacancy at 24.9% in Q2 2026, peaking at a record 25.6% by end-2026 before easing from 2027; Leechiu counted about 80,000 unsold condos in Q3 2026 (a record 82,900 in Q2), and Colliers 32,600 unsold RFO units in Q2. Makati CBD is far tighter, and NCR condo prices still rose 7.4% in Q2 2026 (BSP).
Is Cebu or Davao better for real estate investment?
They suit different goals. Cebu City yields 5.08% gross (Global Property Guide), Metro Cebu condo prices rose 6.4% in Q2 2026 (BSP), and tourism supports short-term rentals, but office vacancy is rising. Davao has 87% condo take-up and lots gaining 13% to 15% a year, but its condo prices fell 1.7% and no reliable yield exists. Cebu for rentals, Davao for land.
Can foreigners invest in Philippine real estate?
Foreigners cannot own land but can own condo units, provided foreign ownership in the project's condominium corporation stays within the legal limit, applied as 40%, under the Condominium Act (RA 4726). RA 12252 (2025) lets foreign investors lease private land for up to 99 years. Budget roughly 3% to 5% for closing costs, more if VAT applies.
Where should OFWs invest in Philippine real estate?
OFW households drive house-and-lot demand in Cavite, Laguna, Batangas and Central Luzon, where Colliers reports take-up of 87% to 96%. Pag-IBIG lends up to ₱10M after 24 monthly contributions, and a representative with a Special Power of Attorney can file for you. House prices in the area fell in Q2 2026 while lots gained 5% to 13% a year, so consider land if appreciation matters most.
Sources and methodology
Last updated October 12, 2026; we will update it after the BSP meetings on October 22 and December 17, 2026 and the Q3 2026 RPPI. Sources: BSP RPPI Q2 2026 and Monetary Policy Report (August 2026); Global Property Guide rental yields (accessed October 12, 2026; asking rents over list prices); Colliers, Leechiu, Santos Knight Frank, CBRE, Savills, PRIME Philippines and Cushman & Wakefield via BusinessWorld (February 2025 to October 2026), attributed because these firms advise developers; Lamudi Journal, Philstar, BPI and Numbeo (July to October 2026). Rail timelines rely on secondary summaries.


